Advertisement
5 ways black tax can delay your financial goals
15th September, 2026 11:19 PM
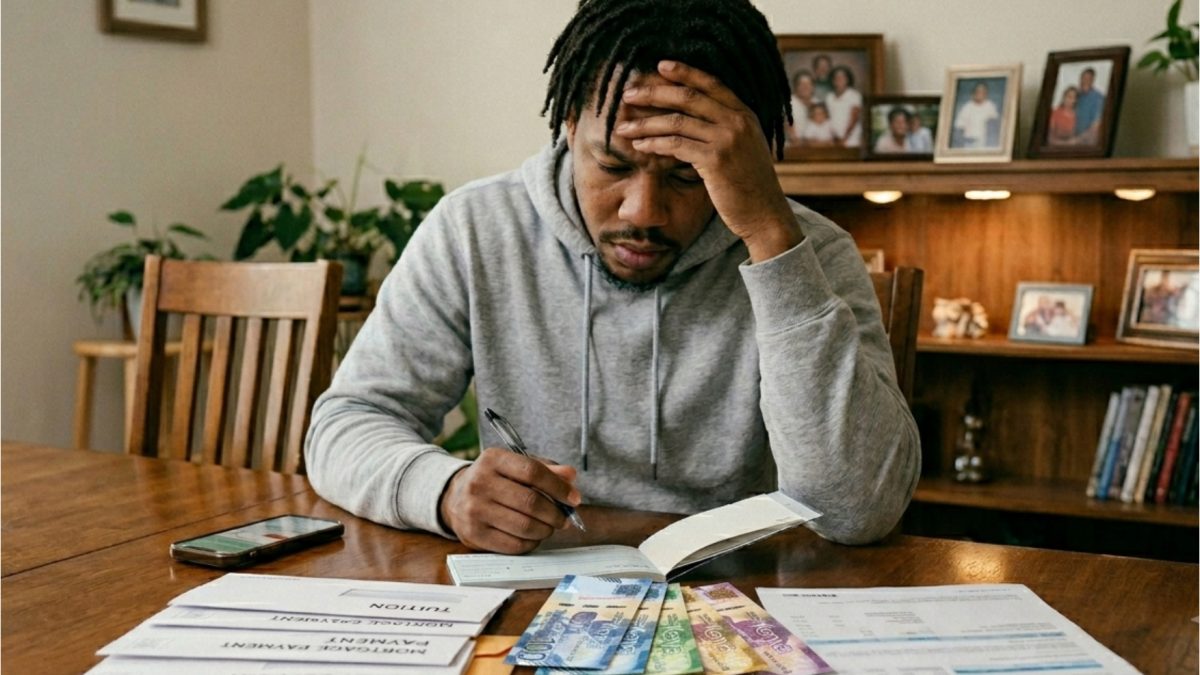
Getting your first job and earning a regular salary can feel like the beginning of financial freedom. But for many young adults, that income comes with another responsibility: supporting parents, siblings and other relatives.
This financial responsibility, often referred to as “black tax”, can be rewarding because it allows people to support their families. However, it can also make it harder to achieve personal financial goals when a large portion of the salary goes towards family needs.
Here are five ways black tax can delay your financial plans.
1. It can reduce your savings
Saving consistently becomes harder when a significant part of your salary is already committed to family expenses.
You may plan to save Ksh10,000 every month, for example, but an unexpected request for school fees, rent, food or medical expenses can force you to use the money.
When this happens repeatedly, building an emergency fund or saving for a specific goal can take much longer.
2. It can delay major purchases
Buying land, building a home, purchasing a car or paying for further education requires careful financial planning.
However, regular family expenses can reduce the amount available for these goals. Instead of putting money towards a long-term target, you may have to prioritise immediate family needs.
This does not necessarily mean the goal is impossible, but it may take longer to achieve.
3. It can make borrowing tempting
When relatives need urgent financial help and your salary is not enough, taking a loan can seem like the quickest solution.
Repeated borrowing, however, can create a cycle where part of every future salary goes towards loan repayments.
This leaves less money for saving, investing and other personal needs.
4. It can limit investment opportunities
Investing requires money that you can afford to leave untouched for some time.
But when most of your income goes towards daily expenses and family support, investing may be pushed to the bottom of the list.
Starting later means you may have less time to benefit from long-term growth.
5. It can change your personal plans
Black tax can affect more than your bank account. It can influence major life decisions.
You may postpone moving out, returning to school, starting a business, travelling or changing jobs because you feel responsible for maintaining a steady income for your family.
Supporting family is important, but it should not mean completely abandoning your own financial future. Setting a realistic amount for family support and including it in your monthly budget can help you plan for both your responsibilities and personal goals.