Advertisement
Why financial independence can look different for men and women
26th September, 2026 12:41 PM
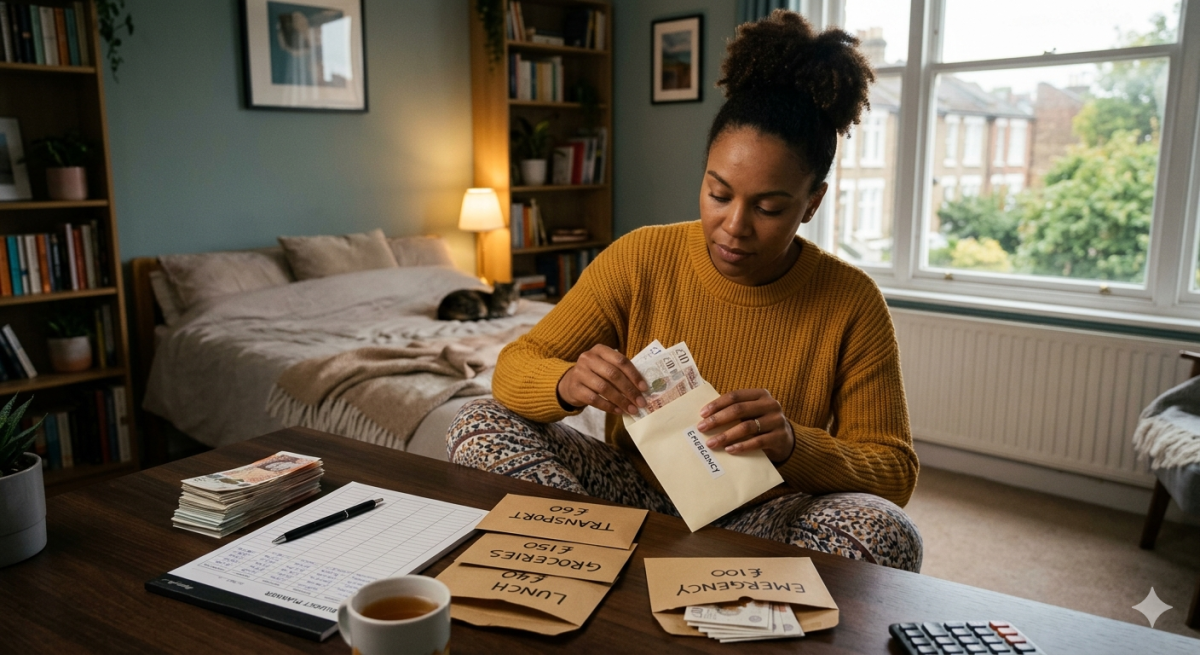
Financial independence does not mean exactly the same thing for everyone. For one person, it may mean earning enough to cover personal expenses without depending on another income.
For another, it may mean owning a home, having enough savings to handle emergencies, or reaching retirement with enough money to maintain a comfortable life.
The path towards that position can also look different for men and women because their working lives, income patterns, family responsibilities, and access to long-term savings are not always the same.
Income can shape the starting point
The amount a person earns has a direct effect on how much they can put towards savings and investments.
Someone with a higher and more consistent income may have more room to build an emergency fund, invest regularly or make large purchases without taking on debt.
Differences in pay can therefore affect financial independence over many years, rather than only affecting what someone can spend in a particular month.

Career breaks can affect long-term savings
Financial independence is also connected to how long someone remains in paid employment.
A career break can reduce current income, but its effect can continue after a person returns to work.
Time away from employment may mean fewer contributions to a pension or investment account and fewer years for those savings to grow.
This can become particularly important when a person takes time away from work to care for children or other family members.
The impact is not the same for every household, and family arrangements vary widely.
However, unpaid care responsibilities can influence how much time people spend in paid employment and how much they are able to contribute towards long-term financial goals.
Retirement can reveal the difference
A person’s financial independence during their working years does not necessarily guarantee the same level of independence in retirement.
Someone may earn a good income for many years but still have limited retirement savings if they did not consistently contribute towards a pension or other long-term investments.
Family responsibilities can change priorities
Financial independence can also be affected by the responsibilities a person takes on.
Supporting children, helping relatives or taking time away from work can change how much money is available for personal savings and investments.
For some households, one income may be used largely for shared expenses while the other person concentrates on building personal savings. In other households, both partners may contribute towards expenses and savings in different proportions.
This means financial independence cannot always be measured simply by looking at someone’s salary or bank balance.
The goal is personal financial security
For both men and women, financial independence can involve having enough control over money to make decisions without being forced into them by a lack of funds.
That may involve building an emergency fund, reducing expensive debt, investing, contributing to a pension and developing more than one source of income.
For women in particular, planning for personal financial security can also be important because longer life expectancy can mean savings need to support a longer period in retirement.
The idea of financial independence therefore goes beyond earning more money. It is also about creating financial options and preparing for periods when income may change.
Men and women may follow different financial paths, but the underlying goal remains similar: having enough resources, savings and financial planning to meet present needs while preparing for the future.